The term "swap" in the context of retail forex trading refers to the interest rate differential between the two currencies being traded. Retail forex brokerage firms often charge or credit traders with a swap rate when they hold a position overnight. This is also known as a rollover or overnight financing fee.
Rollover SWAP
The swap rate is influenced by the interest rate differential between the two currencies being traded. When a trader holds a position overnight, they are essentially borrowing one currency to buy another. The swap rate reflects the cost or benefit of this borrowing.
A swap in forex refers to the interest that you either earn or pay for a trade that you keep open overnight.
Most brokers use the Tom/Next (Tomorrow/Next) adjustment to roll open positions over to the next trading day. The main component forming the Tom/Next rate is the interest rate differential between the currencies. The rollover fees in our simulated trades are dynamically generated from the historical interest rates matching the backtesting session time. For a long EUR/USD position, the daily rollover in USD is approximately: Rollover = Position size (EUR) × exchange rate × (Interest rate of EUR – Interest rate of USD) / 365
For a short position the sign is reversed.
For instance, if the base currency has an interest rate of 5% and the quote currency has a rate of 3%, buying the pair (long the 5% currency against the 3% one) earns the difference: a daily credit of about position size × exchange rate × 2% / 365, before the broker's markup. Selling the pair pays the same amount.
Some brokers apply the swap by adjusting the average open price of the position (in pips/ticks). Others book it as a separate cash credit or debit that appears in your trade report. Either way, the economic effect is the same.
Key points:
- A swap or rollover is the interest earned or paid for a position kept open overnight.
- A rollover/swap is often expressed in pips or ticks (the minimum price move of the contract).
- Check your broker's Overnight Policies, because the swap will vary from broker to broker.
- For FX, the Wednesday rollover is usually charged or credited at a triple rate. Spot settles two business days after the trade, so Wednesday's rollover spans the weekend. Some brokers, and many non-FX CFDs, apply the triple rate on Friday instead. Check your broker's policy.
- Brokers usually add a markup to the interest-rate differential and may charge additional fees (admin fee, financing cost).
Currency SWAPs
While the terminology is similar, retail forex swaps and currency swaps are distinct concepts.
Currency swaps are a different financial instrument involving the exchange of cash flows in different currencies. In the context of retail forex trading, the term "swap" is used to refer to the interest rate differential charged or credited for holding a position overnight.
Don't confuse either with an FX swap, which is a spot trade and a forward trade in opposite directions. The Tom/Next swap that brokers use to roll positions is a one-day FX swap. A cross-currency swap is a longer-term exchange of principal and interest payments in two currencies.
—-------------------—-------------------------------------------
Further reading:
FX spot and swap market liquidity spillovers
BIS (Bank for International Settlements) by members of the Monetary and Economic Department
—-------------------—-------------------------------------------
FX Swaps: IMF (International Monetary Fund)
IMF (International Monetary Fund) FX Swaps: Implications for Financial and Economic Stability Prepared by Bergljot B. Barkbu and Li Lian Ong
Worked example: daily swap on one standard lot of EUR/USD
Assume these illustrative rates (not live data): EUR/USD at 1.1000, a EUR interest rate of 2.00% and a USD interest rate of 4.25%. One standard lot is 100,000 EUR.
Formula (long position, result in the quote currency, USD):
Daily swap = Units × Price × (Base rate − Quote rate) ÷ 365
- Position value in USD: 100,000 × 1.1000 = 110,000
- Rate differential: 2.00% − 4.25% = −2.25%
- Annual carry: 110,000 × −0.0225 = −2,475
- Daily swap: −2,475 ÷ 365 = −$6.78 per night (about 0.68 pips at $10 per pip)
A long position pays about $6.78 a night because you hold the lower-yielding currency. A short position would earn about +$6.78 before costs. The Wednesday rollover is usually tripled, so −$20.34 for the long.
Brokers add a markup. Brokers widen the differential on both sides. With a 0.50% annual markup, the long pays 110,000 × 2.75% ÷ 365 = −$8.29 a night, and the short earns only 110,000 × 1.75% ÷ 365 = +$5.27. Some brokers divide by 360 instead of 365 (−2,475 ÷ 360 = −$6.88). Always check your broker's swap table.
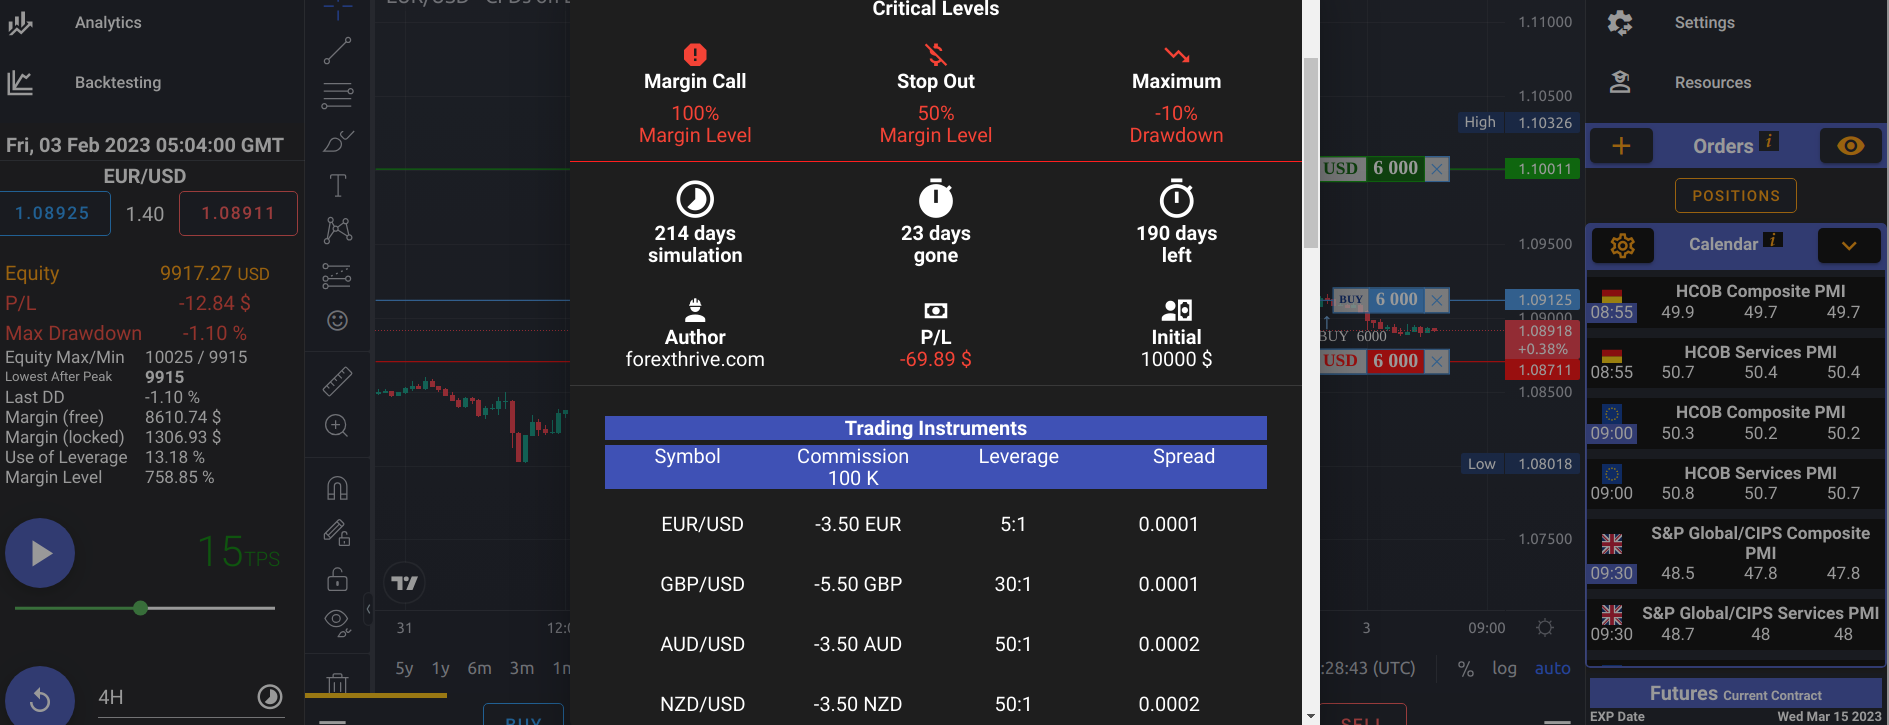
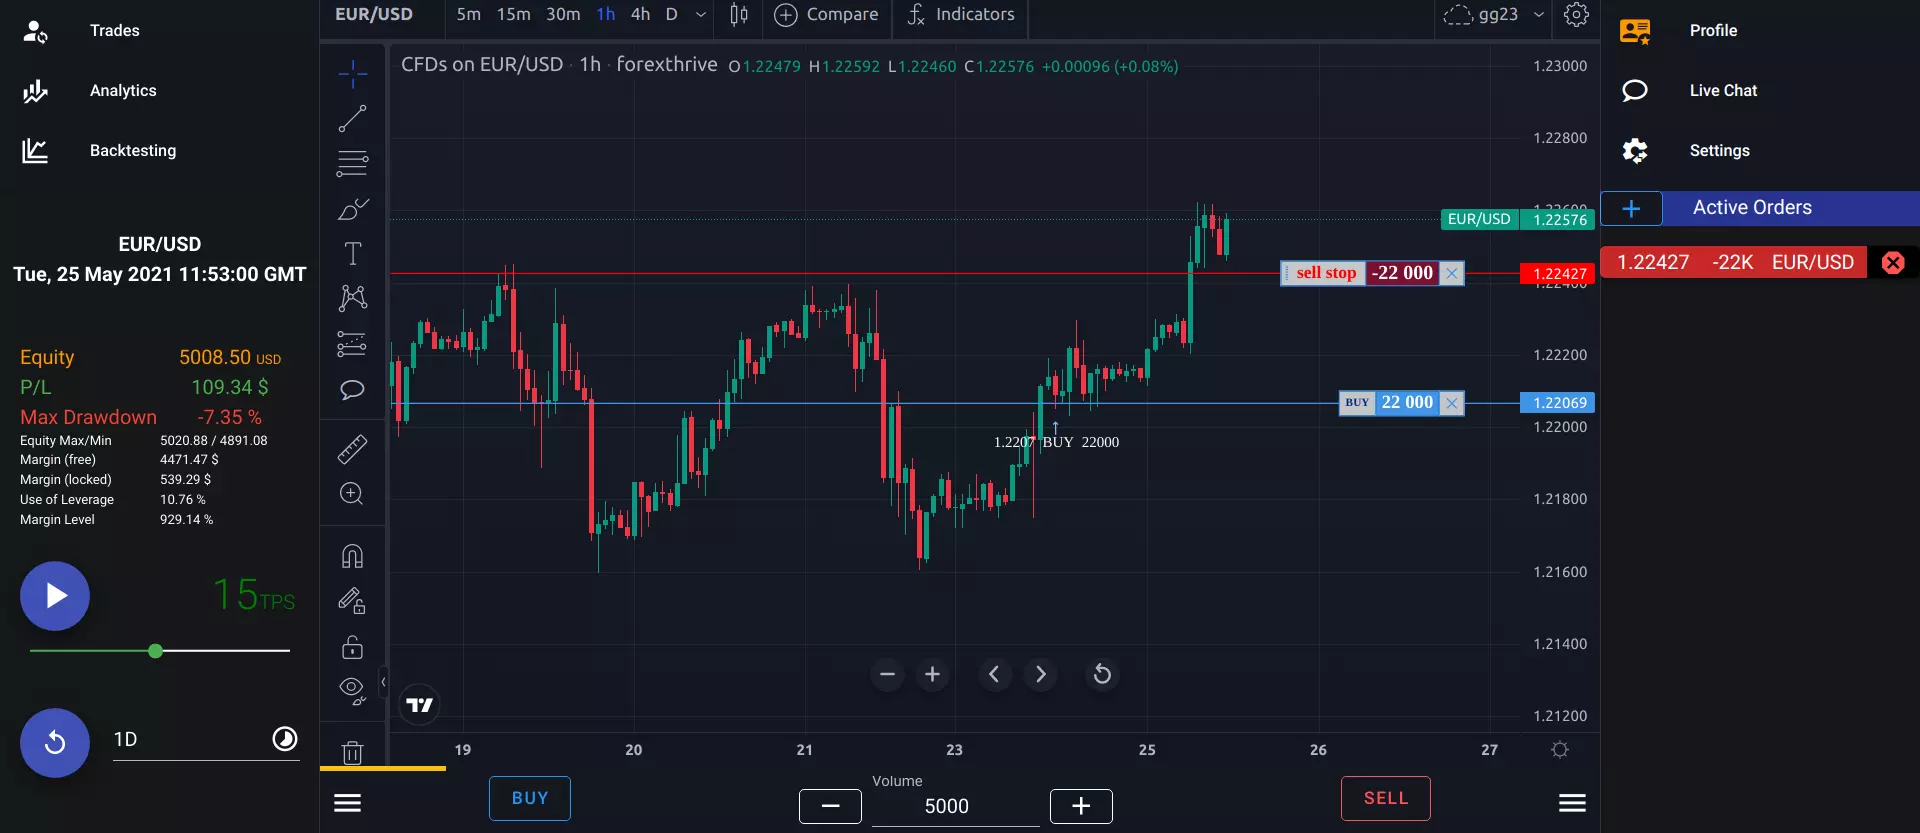
In the ForexThrive simulator, overnight swap is computed from historical interest-rate differentials that match the date of your backtest. That makes carry costs part of the result instead of an afterthought.
Frequently asked questions
How is forex swap calculated?
Per night, swap is about position size × price × (base-currency rate − quote-currency rate) ÷ 365. Some brokers divide by 360. The result is in the quote currency. A long position earns when the base currency's rate is higher and pays when it is lower, and a short gets the opposite sign. Brokers then subtract a markup on both sides.
Why is swap tripled on Wednesday?
Spot FX settles two business days after the trade date. A position rolled on Wednesday moves its value date from Friday to Monday, so it carries three days of interest. Many brokers charge the triple rollover on non-FX CFDs on Friday instead, so check your broker's overnight policy.
What is Tom/Next?
Tomorrow/Next is a one-day FX swap. The position is closed for value tomorrow and reopened for value the next business day. The small price difference between the two legs (the swap points) reflects the interest-rate differential, and brokers pass it on as rollover, plus their markup.
Does the ForexThrive simulator charge swap on backtests?
Yes. Overnight swap in the simulator is computed from historical interest-rate differentials that match the date in your backtest. The app shows historical central-bank rates for CAD, USD, GBP, AUD, NZD, CHF, JPY and EUR, so a carry trade held through 2022 is charged at that period's rates, not today's.
Is a forex rollover swap the same as a currency swap?
No. A retail rollover swap is a nightly interest adjustment on an open position. A cross-currency swap is a separate contract in which two parties exchange principal and interest payments in two currencies over months or years. These are mostly used by banks, corporations and governments.